This site is not affiliated with any government, tax, or other official agency. Form last updated: 07/2026. Please verify you are using the current, correct version for your situation before submitting it.
How it works
1. Open the form
Access the pre-loaded form directly in our PDF editor. No need to upload anything!
2. Fill in your details
Carefully complete all required fields to ensure accuracy and validity.
3. Download as PDF
Save your filled-out form in PDF format, ready for submission or other needs.
What is Form 941-X?
Form 941-X is a crucial document for employers that need to correct errors on a previously submitted Form 941 or Form 941-SS, which reports quarterly federal employment taxes. Employers use it to make adjustments or claim refunds for overpaid payroll taxes. It's important for maintaining accurate tax records and ensuring compliance with IRS requirements. Whether you've overpaid or underpaid, filling out Form 941-X helps rectify payroll tax discrepancies to avoid potential penalties.
What is Form 941-X used for?
Form 941-X is crucial for correcting details on the previously submitted Form 941. Here's what it's used for:
- To adjust wages, tips, and other compensation.
- To correct the reported federal income tax withheld, Social Security taxes, and Medicare taxes.
- To claim a refund or abatement for overpaid taxes.
- To correct employment tax credits (such as the Employee Retention Credit).
- To reclassify workers (for example, from independent contractor to employee).
How to fill out Form 941-X
Follow these Form 941-X instructions:
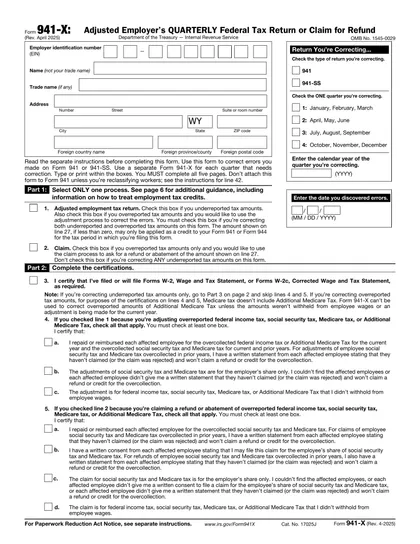
1. Identify the return you're correcting:
Enter your EIN, business name, and address. Check whether you're correcting a 941 or 941-SS, select the one quarter being corrected, enter the calendar year, and the date you discovered the errors.
2. Choose your correction process:
Line 1 (Adjustment): Check this if you underreported taxes, or if you have both underreported and overreported amounts on the same form. The overpayment will be credited to your current quarter's Form 941.
Line 2 (Claim): Check this only if you overreported taxes and want a refund or abatement. You cannot check this box if any underreported amounts appear on the form.
3. Complete the certifications:
Line 3: Certify that you've filed or will file the required W-2 or W-2c forms. If correcting only underreported amounts, skip lines 4–5 and go to Part 3.
Lines 4–5: Check the applicable boxes explaining how you handled overcollected taxes — whether you repaid employees, are adjusting the employer share only, or the tax was never withheld. Line 4 applies if you chose the adjustment process; line 5 applies if you chose the claim process.
4. Enter corrections in Part 3 (lines 6–40):
For each line that applies, enter three columns: Column 1 (corrected total), Column 2 (amount originally reported), and Column 3 (the difference). Column 4 calculates the tax correction — some lines require multiplying by a specific rate (0.124 for Social Security, 0.029 for Medicare, 0.009 for Additional Medicare Tax). If correcting only the employer's share, use half the rate (0.062 or 0.0145). Leave lines blank if they don't apply.
5. Calculate your total (lines 23–27):
Line 27 combines all corrections. If the result is negative and you checked line 1, the amount is credited to your current quarter. If you checked line 2, the amount is refunded. If positive, you owe — pay when you file.
6. Explain your corrections (Part 4):
Line 43 requires a detailed written explanation of how you determined each correction. Check line 41 if any line includes both underreported and overreported amounts. Check line 42 if corrections involve reclassified workers.
7. Sign and date (Part 5):
The return must be signed under penalties of perjury. All five pages must be completed, even if some lines are blank.
Who is required to fill out Form 941-X?
Employers who have discovered errors on previously submitted Form 941 are responsible for filling out Form 941-X to correct those errors.
The IRS uses Form 941-X to process corrections, ensuring employers meet tax obligations accurately.
When is Form 941-X not required?
Not everyone needs to complete the Form 941-X. This form is specifically designed for employers who need to correct errors on previously filed Form 941s.
If you are not an employer or if you have not filed a Form 941 previously, then the Form 941-X is not required for you. Individuals and businesses without employees are examples of those who do not need this form.
When is Form 941-X due?
Form 941-X does not have a fixed quarterly due date. For underreported taxes, file as soon as you discover the error and pay the amount owed at the time of filing. For overreported taxes, you must file within the period of limitations on credit or refund — generally 3 years from the date the original Form 941 was filed or 2 years from the date the tax was paid, whichever is later. If you are within 90 days of that deadline expiring, you must use the claim process (line 2 on the form).
This form is crucial for correcting previously reported employment tax figures, ensuring your business complies with IRS regulations. Remember, timely submission helps avoid potential penalties.
How to get a blank Form 941-X
On our platform, we have a blank Form 941-X template pre-loaded in our editor, ready for you to fill out. This means you don't need to look elsewhere to download the template, making it easier to prepare your document.
Remember, while CookPDF helps you fill out and download the form, it does not assist with filing the form.
How to sign Form 941-X online
To sign the 941-X form on CookPDF, first complete all required fields. Then, select the signature tool from the menu to create your electronic signature.
Follow the prompts to draw or type your signature, and then place it in the appropriate form field.
Where to file Form 941-X?
Form 941-X is used to correct errors on a previously submitted Form 941. As of now, it cannot be submitted online and must be sent by mail. As of July 2024, the IRS began accepting Form 941-X electronically through the Modernized e-File (MeF) system. Check current IRS guidance to confirm which correction scenarios are eligible for e-filing.
You must ensure accuracy when completing Form 941-X. Follow IRS guidelines closely to avoid delays.